Missouri Roof Insurance Claims Guide
Make sense of the roof claim payment without losing sight of the roof work itself.
- Free roof inspections
- Repair and replacement options explained
- Homes, outbuildings and commercial properties
Call about your roof (816) 281-9183
Separate the scope from the settlement
The roof scope says what needs repair or replacement. The insurance policy says which part of a covered loss is payable. Keep those two documents connected without treating them as the same decision.
- Roof work
- A physical repair or replacement recommendation.
- Policy payment
- A coverage decision with deductible, depreciation and conditions.
What changes a roof claim payment
Missouri Department of Insurance guidance explains these terms. Your actual policy and insurer’s decision control the claim.
| Term | What it means for the roof |
|---|---|
| Covered cause of loss | What it means for the roofA policy can cover storm damage while excluding ordinary wear, deterioration or maintenance. A worn roof is not automatically a covered storm loss. |
| Deductible | What it means for the roofThe amount of the covered claim you pay. A percentage deductible uses the policy’s stated basis, not automatically a percentage of the roof repair bill. |
| Actual cash value | What it means for the roofA settlement basis that accounts for depreciation. The roof can have ACV terms even when other parts of the home have replacement-cost coverage. |
| Replacement cost | What it means for the roofA settlement basis without a depreciation deduction for qualifying completed repair or replacement, subject to policy conditions, limits and deductible. |
| Recoverable depreciation | What it means for the roofUnder qualifying replacement-cost terms, an amount initially withheld can become payable after conditions are met. Deadlines and documentation matter. |
The roofing recommendation and the claim decision
A sensible project starts with a dependable roof scope.
What the inspection establishes
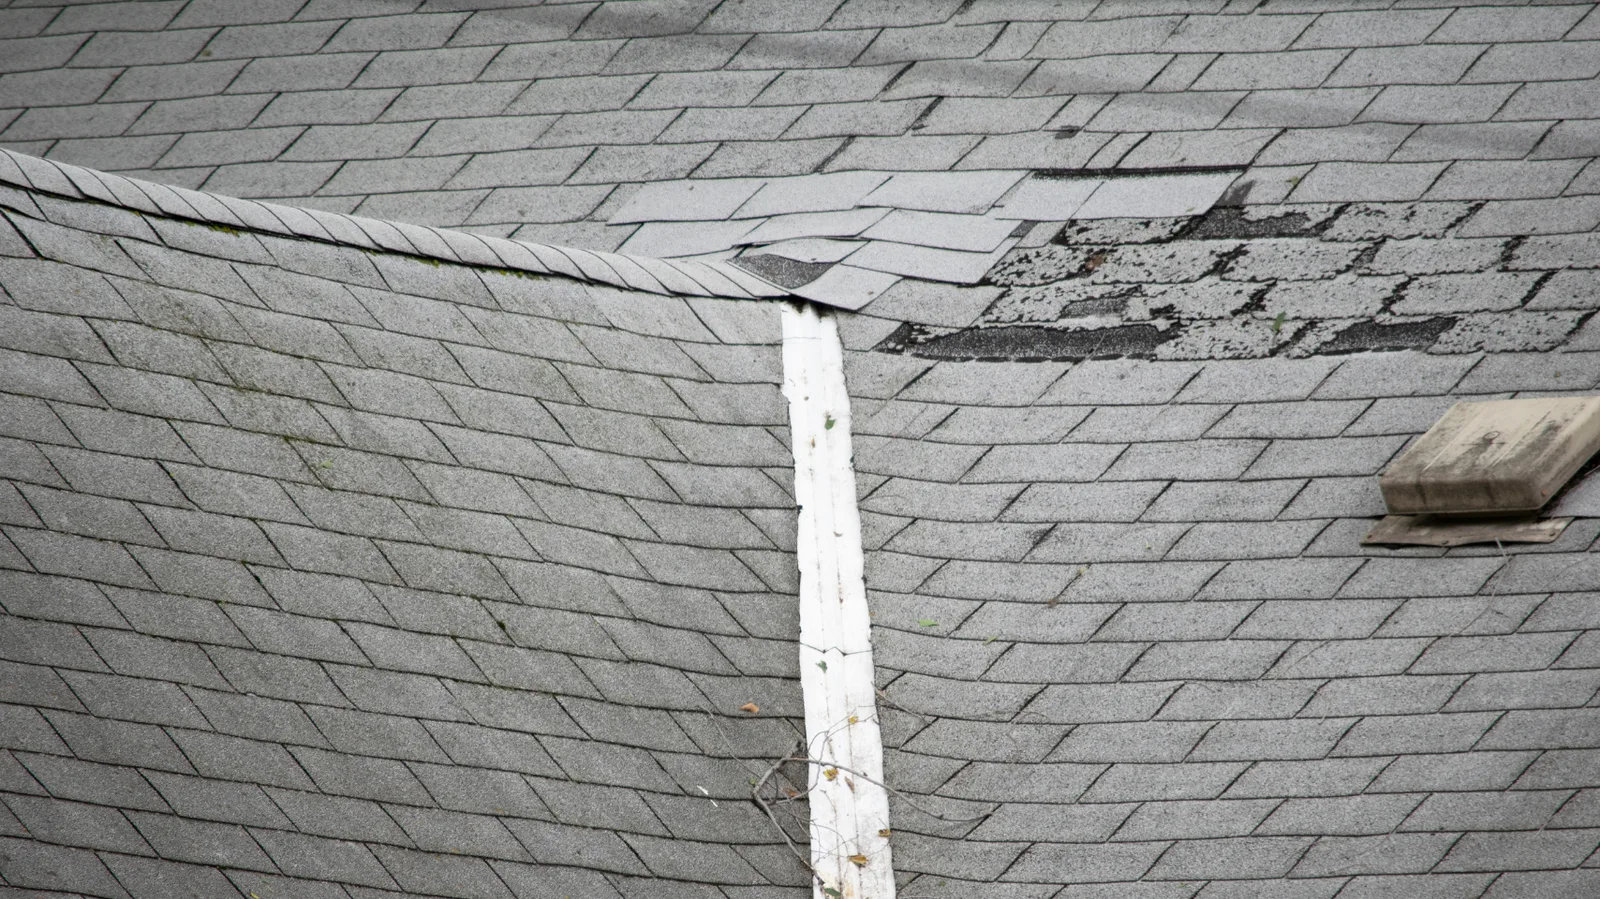
The condition of the covering, flashing and surrounding material informs repairability. Findings can describe damaged components and the work needed without promising policy coverage or attributing every mark to one storm.
What the insurer determines
The insurer applies the policy’s cause, limits, exclusions and settlement terms. Coverage questions, claim disagreements and representation belong with the insurer or an appropriately authorized insurance professional.
Keep the roof work and claim records aligned
You can report what you already know without diagnosing the roof or turning the request into a paperwork exercise.
Protect against further damage safely
Keep away from hazards and mention active water entry when seeking roofing help. Reasonable temporary protection and its records can matter under a policy.
Understand the roof scope
A free inspection gives the work discussion a starting point. The proposed repair or replacement should account for affected layers and compatible materials.
Resolve the policy questions
The insurer explains deductible, depreciation, deadlines and the basis for payment. Project changes and uncovered work need to stay visible rather than be assumed away.
See payment timing in an example
A deductible and depreciation can leave a first payment smaller than the full replacement scope. The claim payment example separates the first payment, potential later depreciation and the owner’s contribution. It uses fictional numbers you can change, not a prediction about your policy.
Read the Missouri Department of Insurance’s roof coverage guidance for the state regulator’s explanation. Try the claim payment explainer to see how the arithmetic works.
Start with the condition of your roof
Call (816) 281-9183 or request a free Raymore roof inspection. The work decision starts with the roof, while the insurer handles policy coverage.